Fire or smoke damage? 24/7 cleanup across King, Snohomish, Pierce & Kitsap counties24/7 fire & smoke cleanup · Puget Sound Call or text (844) 543-5757·info@helpmenow.com
Puget SoundFire Damage
(844) 543-5757
Guide

Replacement cost versus actual cash value

Call me right now

Need help? Request a local contractor

Free · No obligation · You choose who to hire

Handled by HelpMeNow.com, a Help Me Now Inc service. The restoration contractor who calls you is an independent Washington-registered business.

The two numbers that decide what a fire claim pays, and the step in between that most families leave money on.

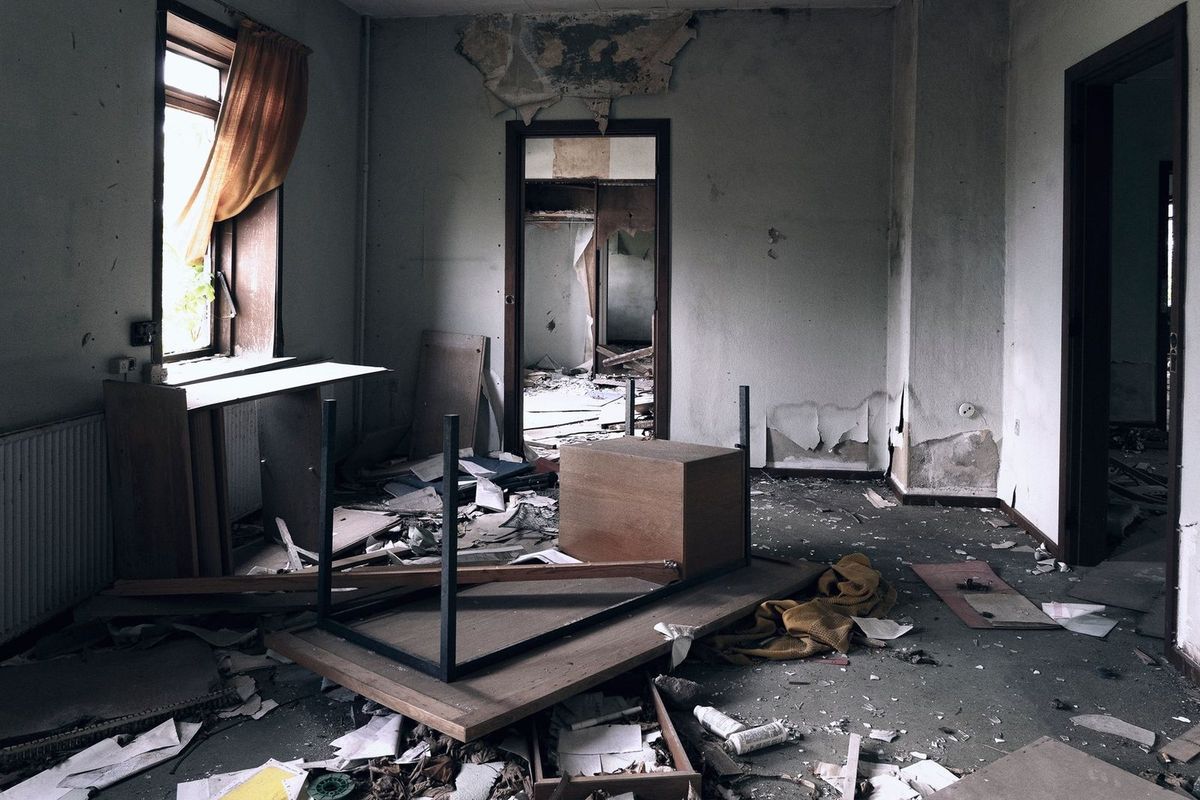
A fire-damaged room stripped to bare walls
Papers and electronics are triaged first; soot keeps corroding.

The building

Most Washington homeowners policies insure the dwelling at replacement cost: the cost to rebuild with like kind and quality today, up to the dwelling limit. The carrier typically pays actual cash value first, the replacement cost less depreciation, and releases the depreciation as the rebuild is completed and documented. If the rebuild costs more than the dwelling limit, extended replacement cost endorsements add a percentage; ordinance or law coverage pays code-required upgrades. If you choose not to rebuild, or to rebuild elsewhere, many policies pay only actual cash value.

Contents

Personal property is paid on the inventory, item by item, at actual cash value first. Replacement cost policies release the withheld depreciation as you replace items and submit receipts. ACV-only policies stop at the depreciated figure. Sub-limits apply to jewelry, firearms, cash, collectibles and similar categories.

Collecting recoverable depreciation

Keep every receipt for replaced items and every contractor invoice. Submit them before the deadline, which is in your policy and often extendable in writing. Replacing an item with a much cheaper one forfeits the difference; replacing with an equivalent collects it. On the building, the contractor's final invoice and inspections trigger the release.

The deadlines that catch people

Recoverable depreciation windows. Proof of loss deadlines, which in Washington are typically set by the policy with the carrier required to provide forms. Appraisal and suit limitation periods for disputes. Ask your adjuster for each date in writing and note them.

Mortgaged homes

Building payments are usually issued to you and your mortgage servicer jointly; the servicer releases funds in draws against inspections. Contact them early and ask for their process.
FAQ

Questions homeowners ask us

What is actual cash value?

Replacement cost minus depreciation for age, wear and condition. It is what most policies pay first, on both the building and the contents.

What is recoverable depreciation?

The difference between actual cash value and replacement cost, withheld until you actually repair or replace, then released when you submit proof. It has a deadline, often six months to a year from the ACV payment, which can usually be extended on request.

Does my policy pay replacement cost?

Check the declarations page. Most homeowners policies pay replacement cost on the dwelling; contents may be replacement cost or actual cash value depending on the policy and endorsements. Older or budget policies are sometimes ACV-only.

Open now

Crews respond 24/7

One call reaches a Washington-registered fire restoration contractor serving Seattle and the Puget Sound region. $0 upfront on covered claims; your insurer is billed directly.

Call now(844) 543-5757
Send us photos

Show us what happened

Add a few photos, tell us where you are and a dispatcher looks at them right away, then calls or texts you back.